In conversation with Tyler Cowen
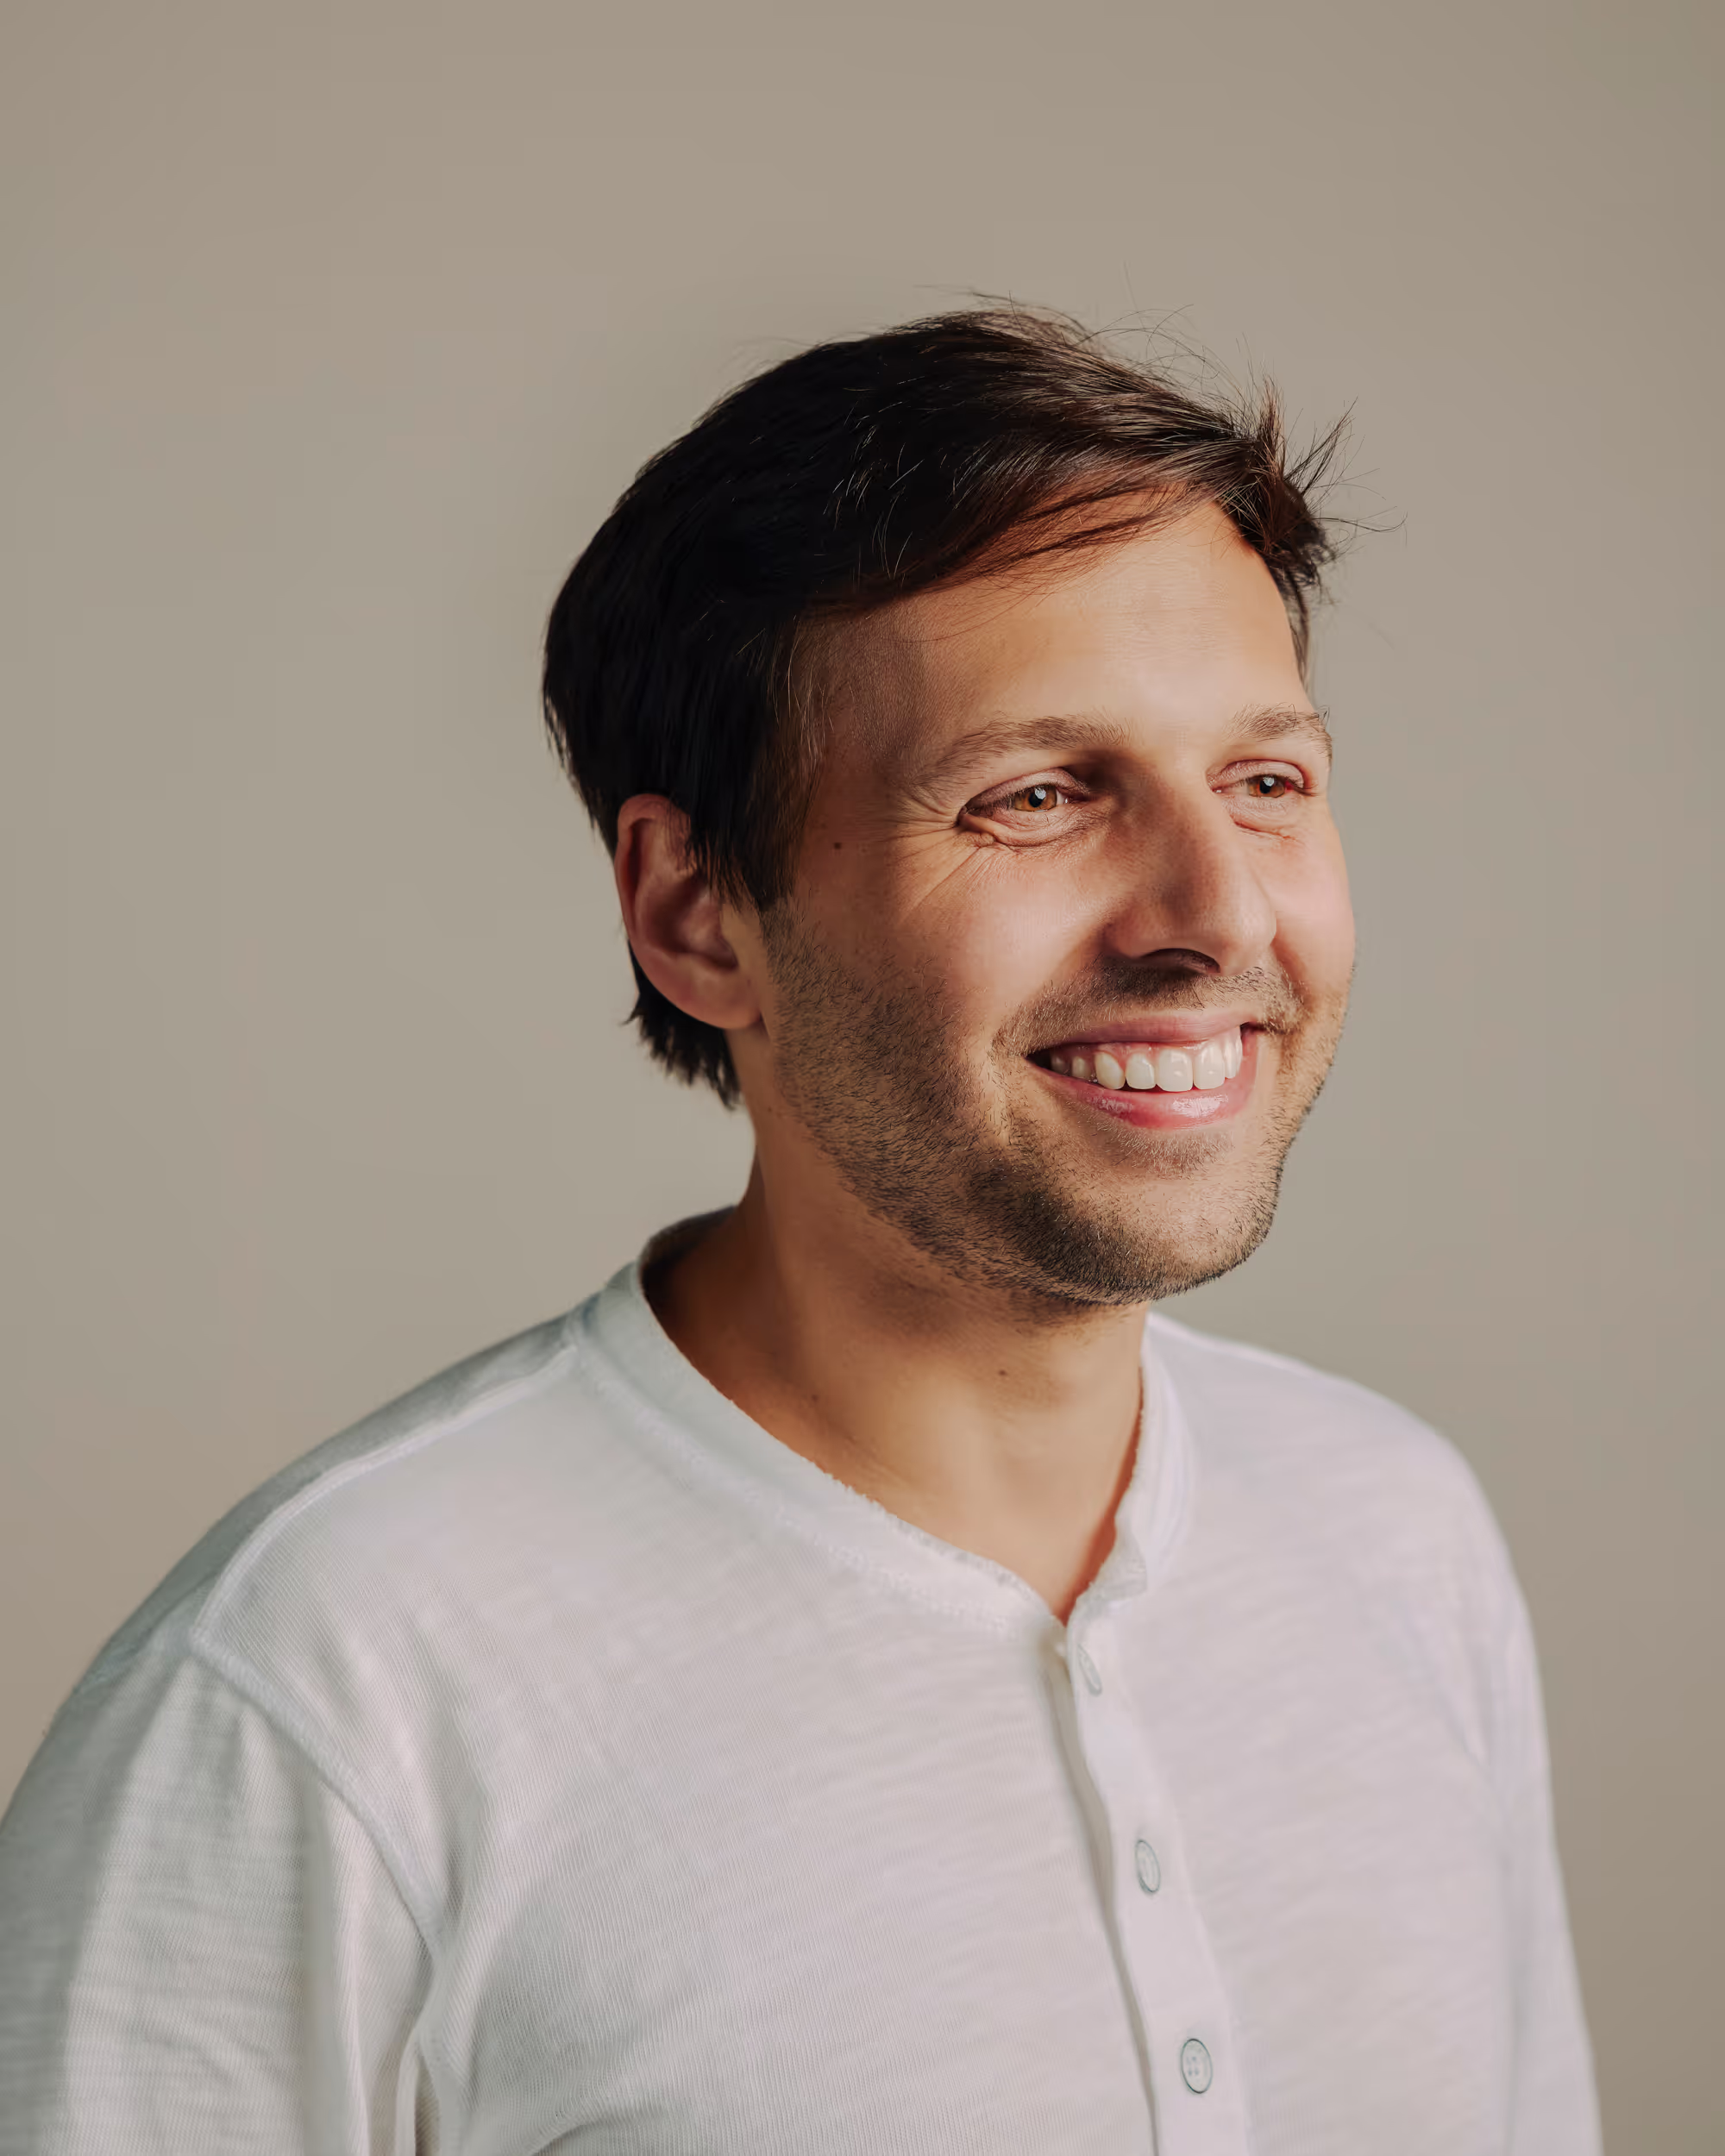

Earlier this year, I had the opportunity to sit down with Tyler Cowen. Tyler is an economist and professor at George Mason University. He is known for his really great blog called Marginal Revolution and podcast called Conversations with Tyler. What I love about Tyler’s work is that it bridges the technical side of AI with the economic and historical lens of how technical revolutions have progressed. We discussed what we can learn from previous patterns of adoption, where the next waves of growth will come from, and what AI will actually do to the economy.
Jeremy Kaufmann: So maybe just start with the idea that you're famous for. I think your statement is literally, "The technology is, in this revolution, the most important of our lifetimes, but it's only going to add half a point to GDP growth over the next couple years." Talk about how that's possible and what you mean by that.
Tyler Cowen: When electricity came along, it took 40 years for electricity to be distributed and used everywhere. In factories, it was a nice thing to have, but you didn't get the full productivity gains until you arranged your whole factory around the notion that you had electricity, and earlier factories didn't have electricity at all. That process took 40 years. I don't think it will take 40 years this time, but it's very striking to me when you look at where AI is succeeding.
So often it is in startups. So a belief in AI is in fact a belief in startups. Startups do not have to take apart their legacy systems. They don't have to get everyone on board. They don't have to fight their human resources departments. The good startups are native AI. And also when you see firms with small numbers of people, occasionally it's even one person. It can be one to five people.
They start off, they use agentic AI. There's not a problem with coordinating the two or three people using agentic AI. They're all on the same page. But if you take an organization of, say, 100 people and say, "Well, don't just freelance with Claude. Claude, write this memo for me." That's fine. That's going great. But you get everyone coordinating around the same uses of AI to restructure entire departments, that is quite slow and often painful and meeting with resistance, or just no one quite knows how to do it in an established firm. So when you work through that logic in the entire economy, my best estimate, and I stress this is an estimate, it is speculation, but AI will give us at first another half a percentage point of growth, which over time compounds to a lot.
But it's not these scenarios you often hear in the Bay Area, like three years later, all white collar workers are out of work, everyone lives to 200, and then 10 years after that, it kills us. It's gonna be a little more normal than that.
Jeremy Kaufmann: So what do you think genuinely brilliant, high IQ individuals working with the technology at the labs are missing in their perspective when they come to different conclusions?
Tyler Cowen: There's the utopians and there's the doomers. I would start with this point. If you look at China or India, where there's a lot of work being done in AI, people's views there are actually fairly close to mine. This will be extremely important, but it won't quite feel as abnormal as many people are expecting.
I think there's something ideological about the Bay Area. On net, it's good and motivating. You saw a different version of it in the 1960s or the Grateful Dead or psychedelic rock and so on. It has serious costs, but that's the way Americans are. There's something millenarian about our outcome, about our mentality, something very dramatic.
A lot of the rest of the world is more pragmatic, and I think here people have just gotten swept up in this social contagion. They're the ones doing it, so there's a sense of being drunk on one's own power and also afraid of what you might be doing, and that interacts with different mental attitudes, and you get what we have.
Jeremy Kaufmann: The classic question you ask in venture is, what would be the data point to prove that your prior is wrong? What would be the first data point that you’d watch for to see if the productivity boom is actually showing up faster? What do you think that would look like?
Tyler Cowen: One thing you can look at is just dispersion of returns. Another thing you can look at is real interest rates. Real interest rates are up a fair amount. It seems to be mostly fiscal troubles since the countries they're going up in are the US, France, and Japan. Some of that is probably the productivity boom, and a lot of money being needed for data centers. So that's an indicator that something is afoot.
But real interest rates are lower than when I got my first mortgage. They're not extraordinarily high by historical standards. You could look at volatility measures for the stock market. Right now, market prices, which are the result of people with real money on the line, are indicating things are going pretty well, but the world still is fairly normal.
Jeremy Kaufmann: Let's move into a couple examples of technology diffusion. I remember in one of your podcasts, you say, "An AI researcher should meet sitting in a faculty senate meeting." What did you mean by that?
Tyler Cowen: Universities are a reasonably large share of the US economy. I live my life in a university. If there's anywhere that should change because of AI, in whichever direction you might think, it's universities. If you just ask yourself, well, what are universities doing right now?
There's a lot of micro activity from particular researchers. That's great. But universities at the level of administration are mostly in denial. You can go to a faculty senate meeting and they talk about, "Should we ban this? Do we need to ban this?" They're obsessed with stopping students from cheating.
I'm by no means for cheating, but if that's your whole forward-looking program for AI, you're failing very badly. And if you just add up sectors of the American economy, like higher ed, basic education, nonprofits, government, there's some other things you could toss in there, but it's thirty to forty percent of the economy that's still in total denial for the most part, or they're just not able to do anything.
I think there's a whole bunch of mayors in the United States who realize something is afoot, but they don't have the money or the talent to really restructure local government that much using AI. So they do the individual freelancing. "Oh, Claude, write my memo for me." And again, that's fine. But when thirty or forty percent of your economy is pretty stuck, that's another sign that growth won't be that rapid. But, the places that have small numbers of people to start with, and are dynamic and AI-first, the winners there will do incredibly well.
Jeremy Kaufmann: So let's turn to the opposite of that 30 to 40%, which are some of the markets we're trying to invest in. What do you think the characteristics are of fast adoption, and where else should we be looking as venture investors?
Tyler Cowen: Well, I think you should look everywhere. I'm a talent-first thinker, so I think the quality of the founder matters above everything else, and AI will in fact come everywhere. So I would look at as many things as possible. But I think high-priced services, sectors where you have partners who earn two or three million dollars a year—I'm not saying they don't work, but a lot of what they're doing is bringing in and maintaining clients. There's typically big rents in those sectors, even when you can count a fairly large number of firms, and that's where I would start.
But most of all, look everywhere, but maybe not higher education.
Jeremy Kaufmann: To go back to the Paul David paper about redesigning business processes in the Industrial Revolution. In that example, why did it take 30 to 40 years to redesign the process? And when you relate it to AI, what do you think process redesign would look like?
Tyler Cowen: With AI, a big part of process redesign is just getting people to understand what AI is, to be awake to it, to having basic facility to manage processes with agents, to know when to check in on agents, to be able to retrain themselves when agents in quality advance very rapidly. That's a big part of it.
So you could learn whatever you need to know today, and it's possible three weeks later, literally three weeks later, you need to learn a whole bunch of new other things. People are not psychologically geared for that. They feel they were not hired for that purpose, and in fact, probably they weren't. So you need a complete re-evolution of what you might call the implicit social contract between these hires.
That happens slowly. It can require employees to be turned over. It can require younger people to come into the company who are more comfortable with AI, or sometimes it's older people who are actually more comfortable. Sometimes the AI is amazing, but it's only amazing when someone knows the context of the company in a way to use it properly. The percentage of people in the company who have that contextual knowledge and can integrate it with the AI can be five or ten percent.
So to fix up all those things is very difficult. Now, you asked earlier about changing factories and getting electricity into factories. The obstacles then were not at all the same. With electricity, for instance, just making it safe was very difficult. A lot of people were electrocuted, and it wasn't good for work or morale.
You had to learn a totally different production process, in a world where there was no internet, no television, no radio. People would learn things on a non-scalable basis, which was extremely slow. That took longer than AI adjustment will take. But again, it's a good starting point. You go back earlier to the printing press. That took two hundred years to really matter in many countries because you had the printing press that was better than scribes. But a single printed book would still cost several months' wages of a typical labor. So elites would read books, and the Bible mattered because the church would pay for it. But the full potential of books, again, took two hundred years to realize or more. It won't be that slow this time again, but that's just a way to norm your expectations.
Jeremy Kaufmann: We've talked a lot about constraints today in the system. What do you think is the number one constraint in AI adoption today? Let’s leave aside the regulatory influence sectors.
Tyler Cowen: Just sense of urgency. The fact that in so many institutions, you do not have decisive leaders who have enough institutional capital to just say, "We're gonna do this," in an almost bullying kind of way and pull everyone along with them.
In startups, you typically do. There's a founder mentality. That's great. But even in the United States, the most entrepreneurial nation ever, most institutions don't work that way.
Jeremy Kaufmann: Who do you think has done it really well?
Tyler Cowen: Well, this is what I didn't expect. I didn't think Muse would be so good and that Meta could bring in the people it did. I know those people. I think they're awesome and brilliant, and I like them. But it wasn't clear to me they could work in a structure that many people consider to be somewhat bureaucratic and idiosyncratic. They created a product that is amazing, that Americans love, and is the agent we've been looking for for personal use.
Not very high-powered things, but ordinary “manage your calendar, send an email, book a flight” things. It may become the industry standard, and that's stunning. Zuck did have the sense of urgency, and he brought in the right people. So, you know, congratulations to them.
Jeremy Kaufmann: Very early on, I think in 2025, even before this generation of models, you looked at the technology and you were kind of like, "This is pretty much AGI already." What did you mean by that?
Tyler Cowen: When I looked at the o3 model from OpenAI, and I gave it varying questions, including economics questions in areas I've worked on, I just thought, "Hey, this is smarter than I am."
It can't do things in the physical world, it was not agentic in the current sense, and it was very spiky. But if it's smarter than I am in a broad range of areas, I'm happy to call it AGI. When I was a kid, AGI just meant the Turing test. Now, in a way, it's never passed the Turing test because it sounds too smart, like it knows too much to be a human. But that's kind of passing the Turing test, I would say.
Jeremy Kaufmann: Jumping back, you talked about the people to make use of AI to move things forward. Say more about what you mean by context. How does a company make use of context, and how do I as an individual bring my context to the model?
Tyler Cowen: Well, there's a lot of knowledge. You could say it's in firms or hidden in firms, and it's not in the AI. The AI simply becoming better won't give it that knowledge.
It's like, who can do what? Who needs a pep talk? What is the history of different things in the company? How do people respond emotionally to different developments? What do you know about the customers, your main clients, and other firms in the sector?
A lot of it's not articulated. It's just a gut feel. There are a lot of people in companies who are perfectly great employees, but they've only been there nine months, and they don't have that contextual knowledge. But maybe the person has been at the company for five to seven years knows these things and it makes them more productive.
So when the AI does the information processing, the problem-solving in an amazing way, you still need someone to tie that in to what the company does. And even before AI, those people are quite scarce. They're very valuable. I'm sure you have them in your company. They are going up in value a lot. But again, their scarcity is part of what slows down diffusion.
Jeremy Kaufmann: What do you think the biggest mistake venture investors are making in this era when it comes to thinking about technology diffusion?
Tyler Cowen: Well, venture investors have done pretty well, so far be it for me to lecture them about mistakes. My sense is this. With AI and rapid improvement, the variance of returns will rise an incredible amount, and I'm not sure all venture investors are ready for that. So the returns to a kind of keenness, observation, and very rapid learning of new things will be much higher than they were even a year or two years ago.
So I think a lot of venture firms won't do well at all and will go under, and a lot more will create very wealthy people and improve living standards for all of America and, indeed, the broader world.
Jeremy Kaufmann: If you go back in history and you look at some of these bubbles, is there something history teaches us on that key metric that we should have our eyes on?
Tyler Cowen: Well, I don't know if I'd call them all bubbles. Cars and railroads did pretty well. Particular companies failed. There's ways of talking about failure that aren't just “bubble.” But I would just say there's psychological contagion in human affairs.
Just like so many people in San Francisco now think the world will end, they've talked each other into it on Twitter. On the optimism side, there's a frothiness. It's pretty normal for there to be overreaction in both directions.
Another thing I would say is that, at this point in our history, many weird things will happen. The value of keeping emotional equanimity has never been higher in our lifetime. Don't get too carried away. You're gonna see a lot of weird things. You've seen some already. Hugging Face, very weird, right? Whatever you think of it. More is coming. Don't panic. Keep a cool head. Analyze analytically.
News from the Scale portfolio and firm